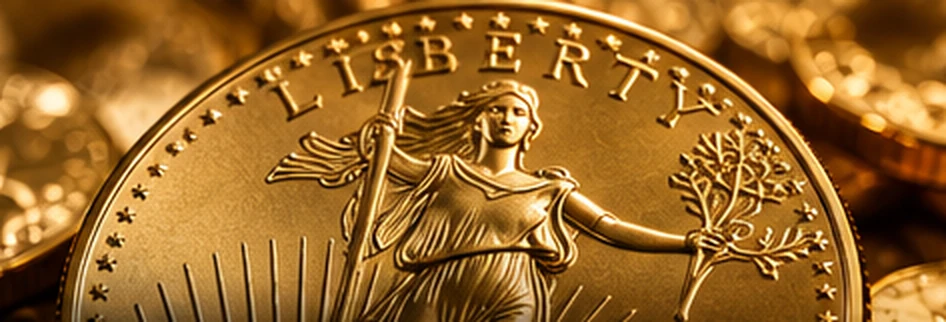
The advertising shorthand is everywhere: “Gold IRA bullion must be 99.5% pure.” Then you encounter an American Gold Eagle, one of the best-known U.S. bullion coins, that the U.S. Mint describes as 22-karat, 91.67% gold—and says investors can include in IRAs. Is somebody misrepresenting the coin or the rules? The answer is more interesting.
The twist: There are different statutory exceptions for specified coins and for qualifying bullion. A Gold Eagle can qualify through the coin exception even though its overall alloy is below a commonly cited bullion-fineness threshold.
Begin with the metal, not the marketing
The U.S. Mint says the one-ounce Gold Eagle contains one troy ounce of pure gold plus small amounts of alloy, with a total weight of approximately 1.0909 troy ounces. Its composition is approximately 91.67% gold, 3% silver and the balance copper. The alloy makes the coin harder-wearing. A 22-karat Gold Eagle is not a secretly underweight coin; its fine gold content and gross weight are different measurements.
That distinction matters when comparing the price of a Gold Eagle with a gold bar. For a one-ounce Eagle, the underlying fine-gold benchmark is based on one troy ounce of gold, even though the complete physical coin weighs more.
Then read the actual law
Internal Revenue Code §408(m) generally treats coins and metals as collectibles; an IRA's purchase of a non-exempt collectible can be treated as a distribution. Section 408(m)(3)(A) carves out certain specifically described coins, including particular gold coins in 31 USC §5112(a). Section 408(m)(3)(B) separately addresses qualifying bullion, including its fineness and the trustee-possession condition.
Using the bullion rule to evaluate every qualifying coin misses the structure of the statute. Conversely, using the coin exception to wave away all custody requirements is equally sloppy. A product's eligibility and an IRA owner's personal handling of it are different legal questions.
Does that mean every gold-colored coin qualifies?
Of course not. “Gold coin” can mean government-issued bullion, a private novelty product, a rare collectible, or even gold-plated base metal. A seller's claim that an object is a legal-tender coin or has a certificate is not a substitute for locating the applicable IRA exception, confirming the actual product, and obtaining acceptance by the IRA trustee.
Consider an American Gold Buffalo: the Mint describes its bullion version as .9999 fine gold. That's a different composition and product design, not evidence that the Gold Eagle is defective. Even among broadly eligible product types, choosing one coin over another depends on retail premium, buyback bid, convenience, and investor preference.
The surprising economic consequence
Imagine a dealer quotes a one-ounce Eagle for $3,000 when the hypothetical fine-gold spot value is $2,700. The $300 difference is a roughly 11.1% markup over the fine-metal benchmark. The alloy doesn't entitle the dealer to count 1.0909 ounces as pure gold. The fine gold content is still the correct gold-value comparison.
A second dealer might quote an entirely different premium or buyback bid. Those prices are fictional examples for the formula, not market averages. What matters to a buyer is the full round-trip cost: purchase premium, recurring IRA fees, and the price available when selling.
Two questions every dealer should answer
First: What exact product is being delivered, and which exception do you believe applies? Ask the custodian to confirm the coin's acceptance independently.
Second: How much fine gold is represented, how much am I paying above the metal benchmark, and what would you pay to buy it back today? Keep purchase and sale quotes in writing.
Why this belongs on a retirement education site
The paradox shows why blunt slogans underperform careful explanation. The rules are specific; the accounting is specific; the spreads are specific. A legitimate product can still be overpriced, and a beautiful coin can still be unsuitable for someone's retirement goals.
If the dealer answers the purity question confidently but won't give the premium or buyback bid, you have learned something useful about the sale. See which gold products may qualify and analyze the complete quote.
Primary sources and review notes
Reviewed October 30, 2026. Verify current rules and account documents before acting. Fee and performance examples are hypothetical. IRA Gold is not a tax, legal or investment adviser.